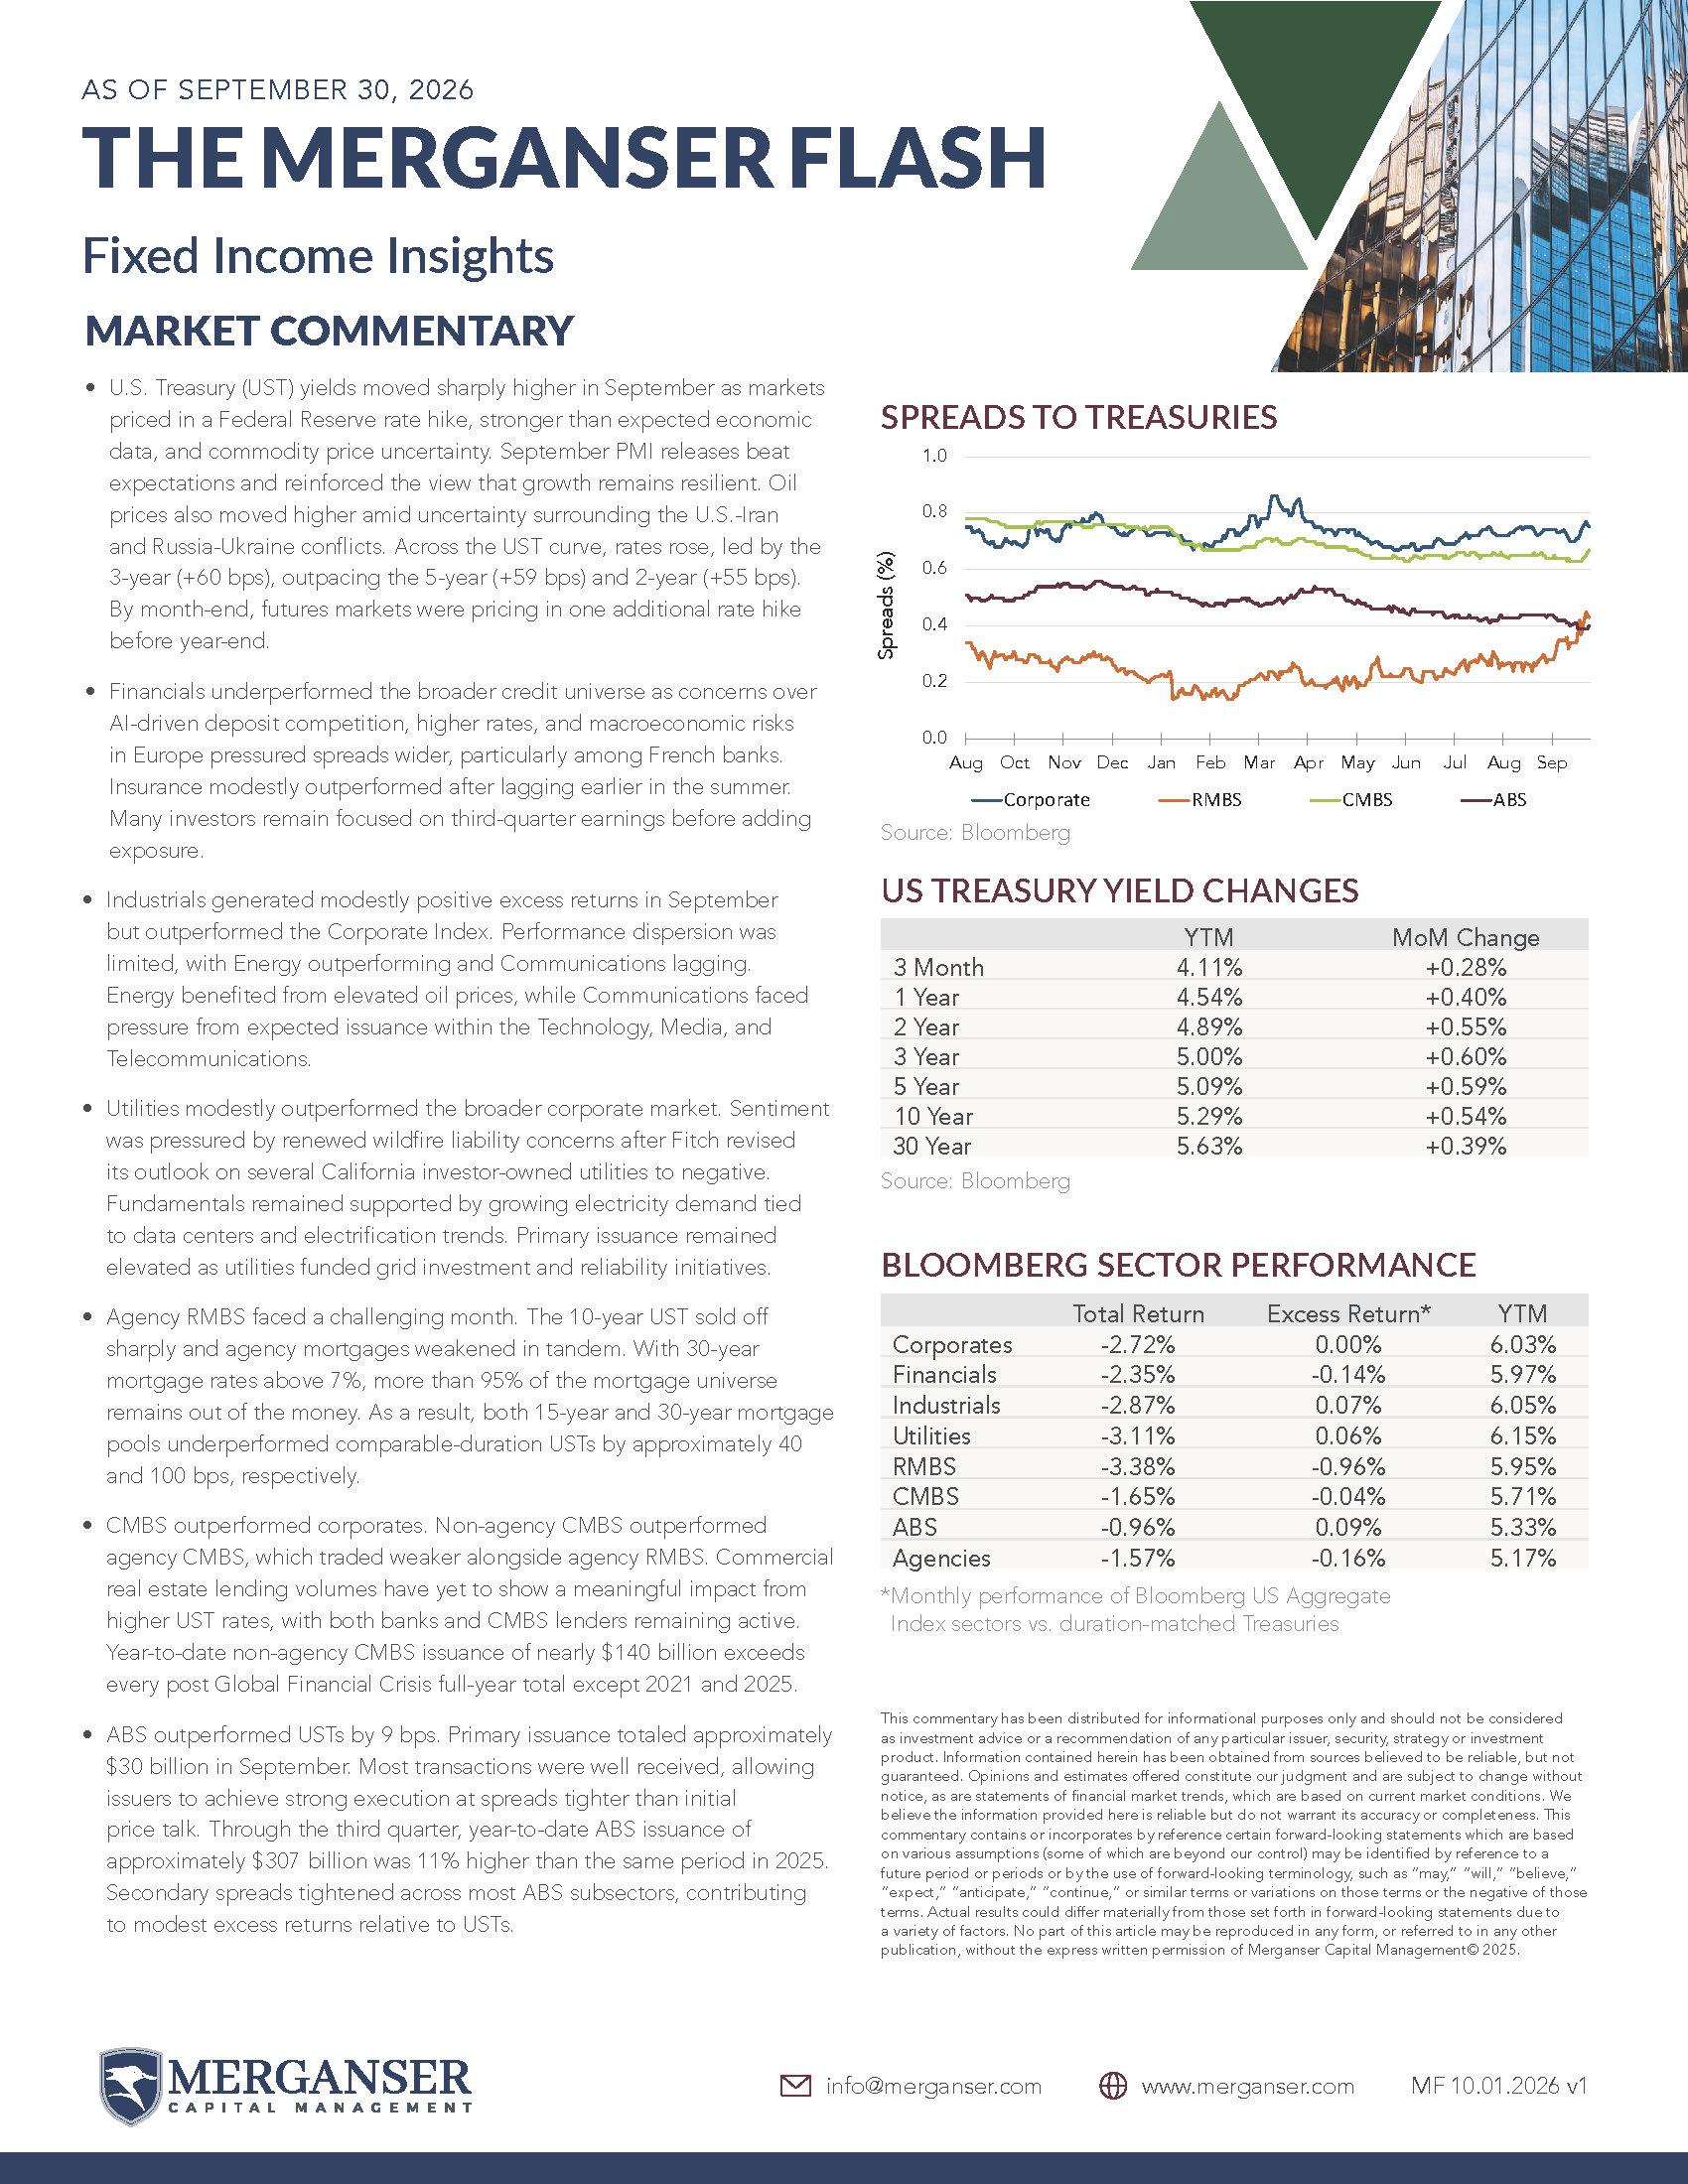
- U.S. Treasury (UST) yields moved sharply higher in September as markets priced in a Federal Reserve rate hike, stronger than expected economic data, and commodity price uncertainty. September PMI releases beat expectations and reinforced the view that growth remains resilient. Oil prices also moved higher amid uncertainty surrounding the U.S.-Iran and Russia-Ukraine conflicts. Across the UST curve, rates rose, led by the 3-year (+60 bps), outpacing the 5-year (+59 bps) and 2-year (+55 bps). By month-end, futures markets were pricing in one additional rate hike before year-end.
- Financials underperformed the broader credit universe as concerns over AI-driven deposit competition, higher rates, and macroeconomic risks in Europe pressured spreads wider, particularly among French banks. Insurance modestly outperformed after lagging earlier in the summer. Many investors remain focused on third-quarter earnings before adding exposure.
- Industrials generated modestly positive excess returns in September but outperformed the Corporate Index. Performance dispersion was limited, with Energy outperforming and Communications lagging. Energy benefited from elevated oil prices, while Communications faced pressure from expected issuance within the Technology, Media, and Telecommunications.
- Utilities modestly outperformed the broader corporate market. Sentiment was pressured by renewed wildfire liability concerns after Fitch revised its outlook on several California investor-owned utilities to negative. Fundamentals remained supported by growing electricity demand tied to data centers and electrification trends. Primary issuance remained elevated as utilities funded grid investment and reliability initiatives.
- Agency RMBS faced a challenging month. The 10-year UST sold off sharply and agency mortgages weakened in tandem. With 30-year mortgage rates above 7%, more than 95% of the mortgage universe remains out of the money. As a result, both 15-year and 30-year mortgage pools underperformed comparable-duration USTs by approximately 40 and 100 bps, respectively.
- CMBS outperformed corporates. Non-agency CMBS outperformed agency CMBS, which traded weaker alongside agency RMBS. Commercial real estate lending volumes have yet to show a meaningful impact from higher UST rates, with both banks and CMBS lenders remaining active. Year-to-date non-agency CMBS issuance of nearly $140 billion exceeds every post Global Financial Crisis full-year total except 2021 and 2025.
- ABS outperformed USTs by 9 bps. Primary issuance totaled approximately $30 billion in September. Most transactions were well received, allowing issuers to achieve strong execution at spreads tighter than initial price talk. Through the third quarter, year-to-date ABS issuance of approximately $307 billion was 11% higher than the same period in 2025. Secondary spreads tightened across most ABS subsectors, contributing to modest excess returns relative to USTs.